Buying A Home And Insurance Costs
Understanding Home Insurance Costs Before Buying a Property
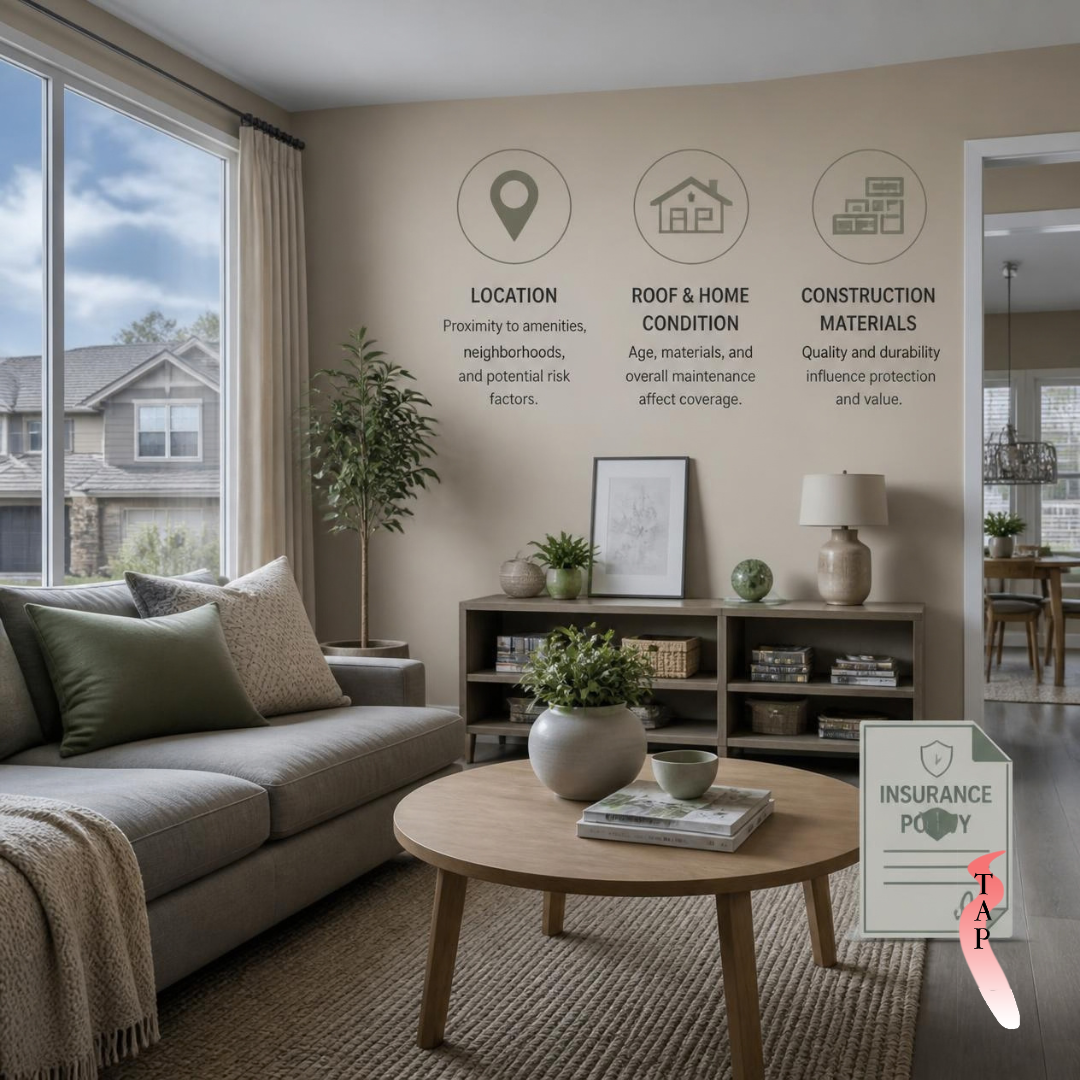
Home insurance can be an important ongoing expense for property owners, but the cost can vary significantly between homes. When comparing properties, buyers should consider not only the purchase price and regular housing expenses, but also how the property's location, construction, condition, and insurance needs could affect premiums.
Understanding the factors that influence home insurance costs can help buyers ask better questions and develop a more complete picture of the ongoing costs associated with a property.
Location Can Affect Insurance Costs
Where a property is located can have a significant influence on insurance premiums. Insurers may consider the property's exposure to risks such as flooding, wildfires, hurricanes, severe storms, or other natural hazards.
Properties in areas with a higher likelihood of certain weather-related events may have different insurance costs or coverage considerations.
The property's proximity to emergency services can also be relevant. Factors such as access to fire protection and the distance to emergency facilities may be considered by insurers.
Property Condition and Age
The age and condition of a home can influence how insurers assess risk. Older roofs, plumbing, electrical systems, heating equipment, and other major components may require closer attention.
A well-maintained property may have different insurance considerations from a similar property with aging or poorly maintained systems.
When buying an older home, it can be useful to understand the age and condition of major components and whether they have been repaired or replaced.
Construction Type and Materials
The way a home is built can also affect insurance costs. Construction materials, structural features, roof type, and other characteristics may influence how the property performs against certain risks.
For example, materials and construction methods can affect a home's vulnerability to fire, wind, storms, or other hazards.
Buyers should consider the property's construction characteristics when comparing insurance quotes for different homes.
Coverage Levels Matter
Insurance costs are also influenced by the amount and type of coverage selected. A policy may cover certain types of property damage, personal belongings, liability, or other risks, depending on its terms.
Higher coverage limits or additional coverage options can affect the premium.
It is important to understand that policies can have exclusions, limits, deductibles, and conditions. The cheapest premium may not provide the same coverage as another policy.
Weather and Natural Hazard Risks
Weather-related risks deserve particular attention when evaluating a property.
Depending on the location, buyers may need to consider risks such as:
- Flooding
- Wildfires
- Severe storms
- Hurricanes
- Tornadoes
- Hail
- Earthquakes
Not all risks are necessarily covered under a standard homeowners policy. Certain hazards may require separate coverage or additional consideration, depending on the location and insurer.
Deductibles Can Affect Costs
A deductible is the amount a policyholder may be responsible for paying toward a covered claim before the insurer pays the remaining eligible amount.
Policies with different deductibles can have different premium costs. However, choosing a higher deductible can also mean having a larger out-of-pocket expense when making an eligible claim.
Buyers should consider both the premium and the potential deductible when comparing policies.
Get Insurance Information Before Buying
Insurance costs are worth investigating before committing to a property. Buyers can request quotes using the property's specific characteristics and location rather than relying on general estimates.
Providing accurate information about the home, including its age, construction type, roof, systems, location, and previous claims where relevant, can help produce a more useful estimate.
Insurance costs can also change over time, so a current quote should not be treated as a guarantee of future premiums.
Consider Insurance Alongside Other Homeownership Costs
Home insurance is only one part of the ongoing cost of owning a property. Buyers may also need to account for property taxes, utilities, maintenance, repairs, association fees where applicable, and other recurring expenses.
Looking at these costs together can provide a more realistic view of what owning a particular property may involve.
Ultimately, home insurance costs depend on several factors, and two otherwise similar properties may have different premiums. Researching insurance early and understanding what influences the price can help buyers make a more informed assessment of a property's ongoing expenses.